This is an edition of The Atlantic Daily, a newsletter that guides you through the biggest stories of the day, helps you discover new ideas, and recommends the best in culture. Sign up for it here.
The political strategist James Carville once joked that if he ended up being reincarnated, he’d like to come back as the bond market. “You can intimidate everybody,” he said.
Not Scott Bessent. About a month ago, during a talk at Southern Methodist University, the Treasury secretary issued a challenge—both to the business-school students in the audience and to the traders of the world. “I have asymmetric information. I am the house now,” he said. “You can bet against me if you want.” The line was an attempt to explain the government’s decision to boost the Japanese yen over the summer, but it was also a broader statement about his ability to influence markets and guard against financial downturns.
This past weekend, Bessent conceded that “the house doesn’t win every hand”—a sign that he’s been slightly chastened. Emphasis on slightly: Although he admitted he “can’t control the bond market,” he maintained that the house still wins “over time.” The bond market’s behavior over the past month clearly called for an adjustment to his posture. The interest rates on the 10-year Treasury (which dictates rates on certain consumer loans) and the 30-year Treasury (an important measure of how investors feel about the government’s ability to pay back its debts) are now the highest they’ve been since 2002. The Trump administration’s market interventions, which have been ramping up in recent months, have had little effect on bond prices. Bessent may continue to insist that he’s the “house,” but it’s clear at this point that the market isn’t listening.
The rates on all kinds of everyday loans are closely tied to what goes on in the Treasury market. When holding government debt starts feeling like a riskier proposition, people start demanding bigger payouts—and when yields increase, consumers pay the price. Looking to buy a house? The average rate on a standard 30-year mortgage is now about 7.5 percent, the highest it’s been in almost three years. Mortgage costs are directly tied to the 10-year Treasury note—and before the war in Iran began driving up yields, the average mortgage rate had just dipped under 6 percent. What about a car? CNBC is reporting that rates on auto loans, some of which are already ticking up, are likely to rise even more as yields on five- and 10-year Treasurys continue to spike.
Yields are up for a few reasons, one of which has to do with massive ongoing expenditures in the AI sector. Companies are laying the groundwork for decades of further investment in the American tech industry, and the Federal Reserve is expected to respond to the economic boost with higher interest rates to curtail inflation. Inflation is a major concern for traders—it has jolted upward as a result of the Iran war, making the Fed even more hawkish. Yields may also be up because of concerns about the $40 trillion national debt. The deficit is about 6 percent of GDP right now, and the government’s borrowing costs are skyrocketing; it currently spends more on debt financing than it does on defense or Medicare. Although there’s some debate around how much the current deficit panic is affecting bond yields, the market could be signaling that this level of spending is unsustainable.
As Bessent rightly points out, he can’t single-handedly determine what happens in the bond market. That hasn’t stopped him from trying. Over the past couple of months, the Treasury has taken steps to expand its regular bond-buyback program. Usually, these buybacks are intended to keep the Treasury market liquid, but many commentators suspect that these moves were really about managing bond prices. When the government uses its own spending power to purchase Treasurys, it can send a signal to the market that prices ought to go up, and yields ought to come down. Lately, though, the buybacks have had the opposite effect. Despite these supercharged interventions, yields have continued to rise, and Bessent has been taking heat for it on Wall Street. He seems unfazed: “If some of the Bloomberg Terminal bros are unhappy with what I’m doing, well, that’s too bad,” he told Steve Bannon last month.
As Bessent digs in, he’s being undercut by his boss’s erratic decision making. Treasury yields tend to go up when foreign bondholders lose trust in the U.S. economy—and Donald Trump’s trade war with Canada, on-again-off-again tariffs, flagrant federal-budget increases, and general air of unpredictability are all points against him. (The president made the unusual suggestion this summer that the military could somehow be used to tame yields.) Plus, the Iran war has driven up consumer prices and raised yields on government debt around the world.
Most voters think the president has hurt the economy, and rising borrowing costs won’t make people any happier. In the meantime, the administration doesn’t seem ready to face reality. Kevin Hassett, the director of the National Economic Council, said he doesn’t “buy” the negative polling on the economy, and Trump continues to insist that the country is experiencing “the best economy we’ve ever had.” Bessent is doing his part to inspire confidence, but the house seems to be down on its luck.
Related:
- Blame Trump for rising borrowing costs, David Frum argues.
- Economists who weren’t worried about the debt are now panicking.
Here are three new stories from The Atlantic:
- A Trump rally stuck in time
- The violence sweeping France was never really about schools.
- Trump is considering a plan to strike Iran before the midterms.
Today’s News
- A Tennessee judge ordered the state to preserve evidence from the botched execution of the death-row inmate Christa Pike, who survived two doses of pentobarbital last week, granting an emergency request from her attorneys. Pike is now conscious and speaking, according to her attorneys, who say she faces a long recovery.
- Russia said it found no safety breaches at a Siberian anti-plague lab after a researcher died from unexplained pneumonia last week, and tests have found no dangerous pathogens. U.S. and World Health Organization officials have pressed Russia for more information about the case.
- Trump wants to turn part of his West Palm Beach golf club into an official presidential retreat modeled after Camp David. The proposal would designate part of the property as an official “U.S. Presidential Golf Course,” and the rest would remain privately owned by the Trump family.
Evening Read
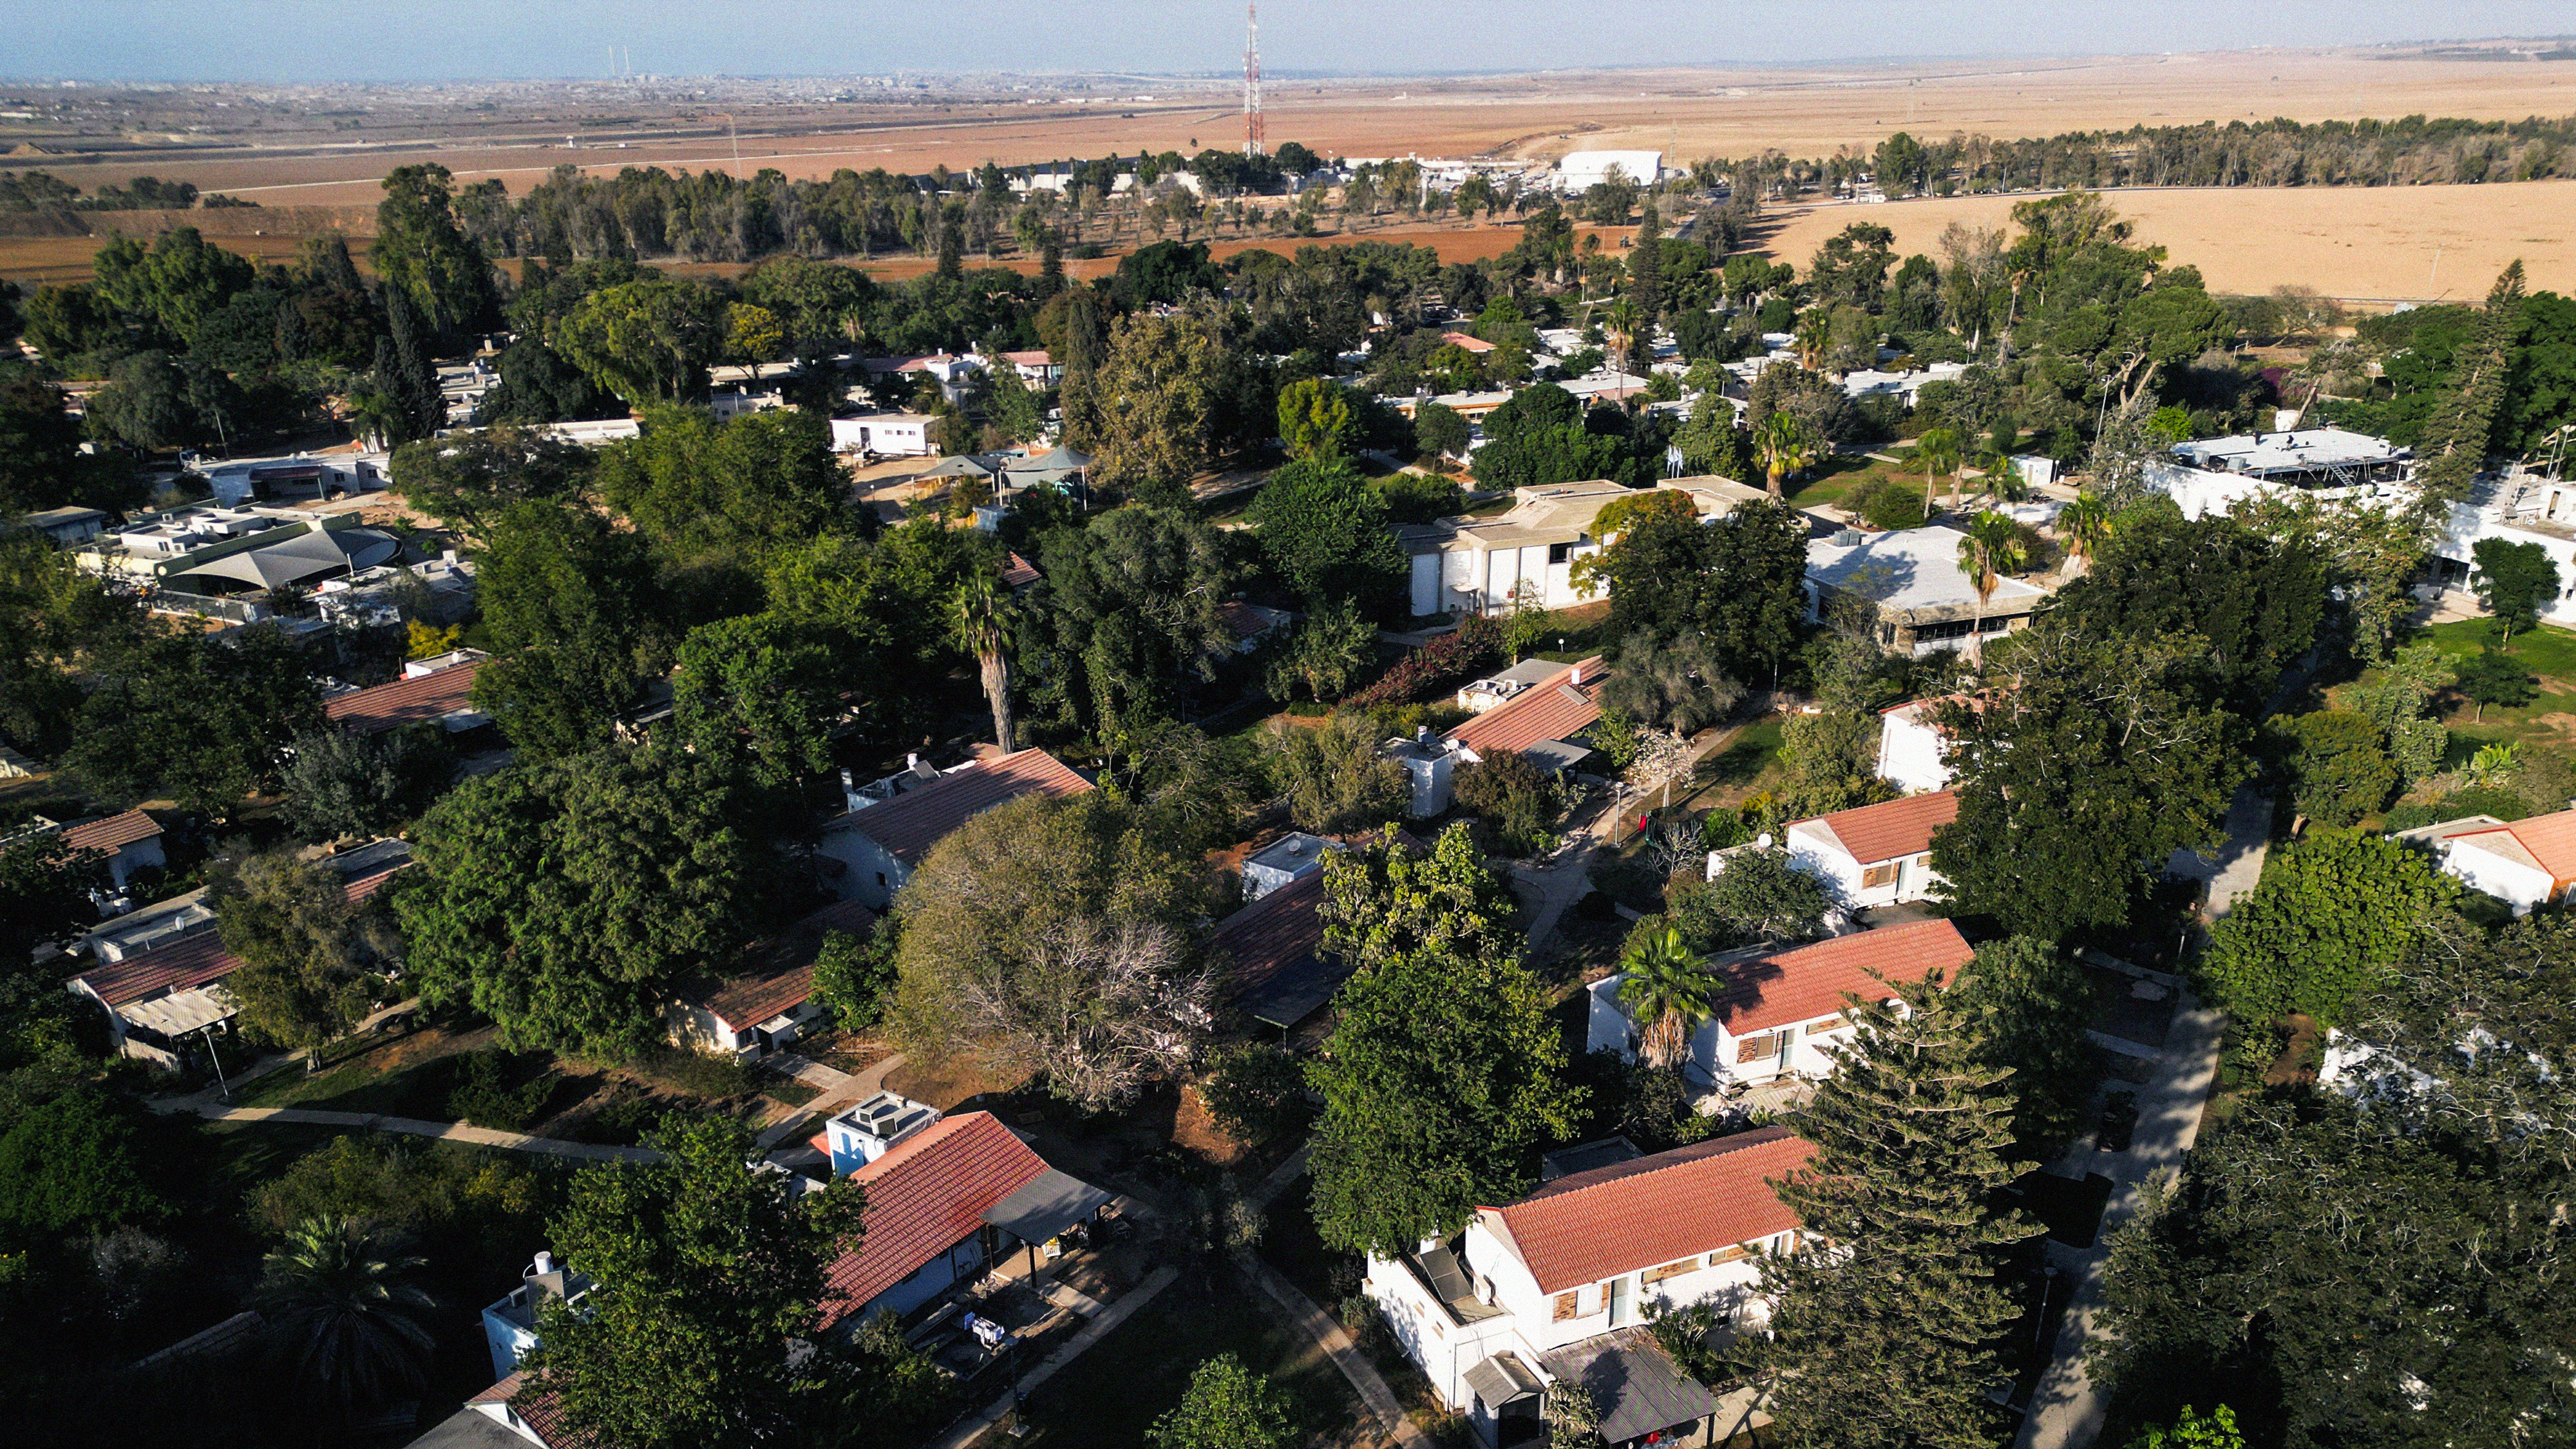
Three Years After October 7, I Moved Back to Nahal Oz
By Amir Tibon
On the morning of August 18, shortly after 10 a.m., a moving truck stopped in front of our home in Kibbutz Nahal Oz, the closest Israeli community to the Gaza border. The driver and two assistants began unloading dozens of boxes containing our belongings—books, clothing, electronics, kitchen appliances.
Fifty minutes later, everything was off the truck, the boxes piled in the center of our living room. I gave the movers some cold water—it was ridiculously hot, as summer days in Israel tend to be—and they hurried out the door. My wife and I stood in front of the boxes, and we both took a deep breath. Almost three years after surviving the October 7 attack, we were back home.
More From The Atlantic
- Gal Beckerman on why you should watch Fauda’s October 7 episodes
- Something like people, a poem by Alexandra Petri
- How long until AI hacks everything?
- Occam’s Razor explains Trump’s daylight-savings obsession.
- The David Frum Show: Why American cities cost so much and deliver so little
Culture Break
Debate. Aaron Sorkin’s The Social Reckoning (out in theaters this week) misunderstands what made The Social Network so compelling, David Sims argues.
Watch (or skip). The climax of the new Carrie series (streaming on Prime Video) has a few of the famous details: prom, pig’s blood, a brutal rampage. But Mike Flanagan’s adaptation drains that moment of its catharsis, Emma Stefansky writes.
Rafaela Jinich contributed to this newsletter.
When you buy a book using a link in this newsletter, we receive a commission. Thank you for supporting The Atlantic.
The post Bessent vs. the Bond Market appeared first on The Atlantic.