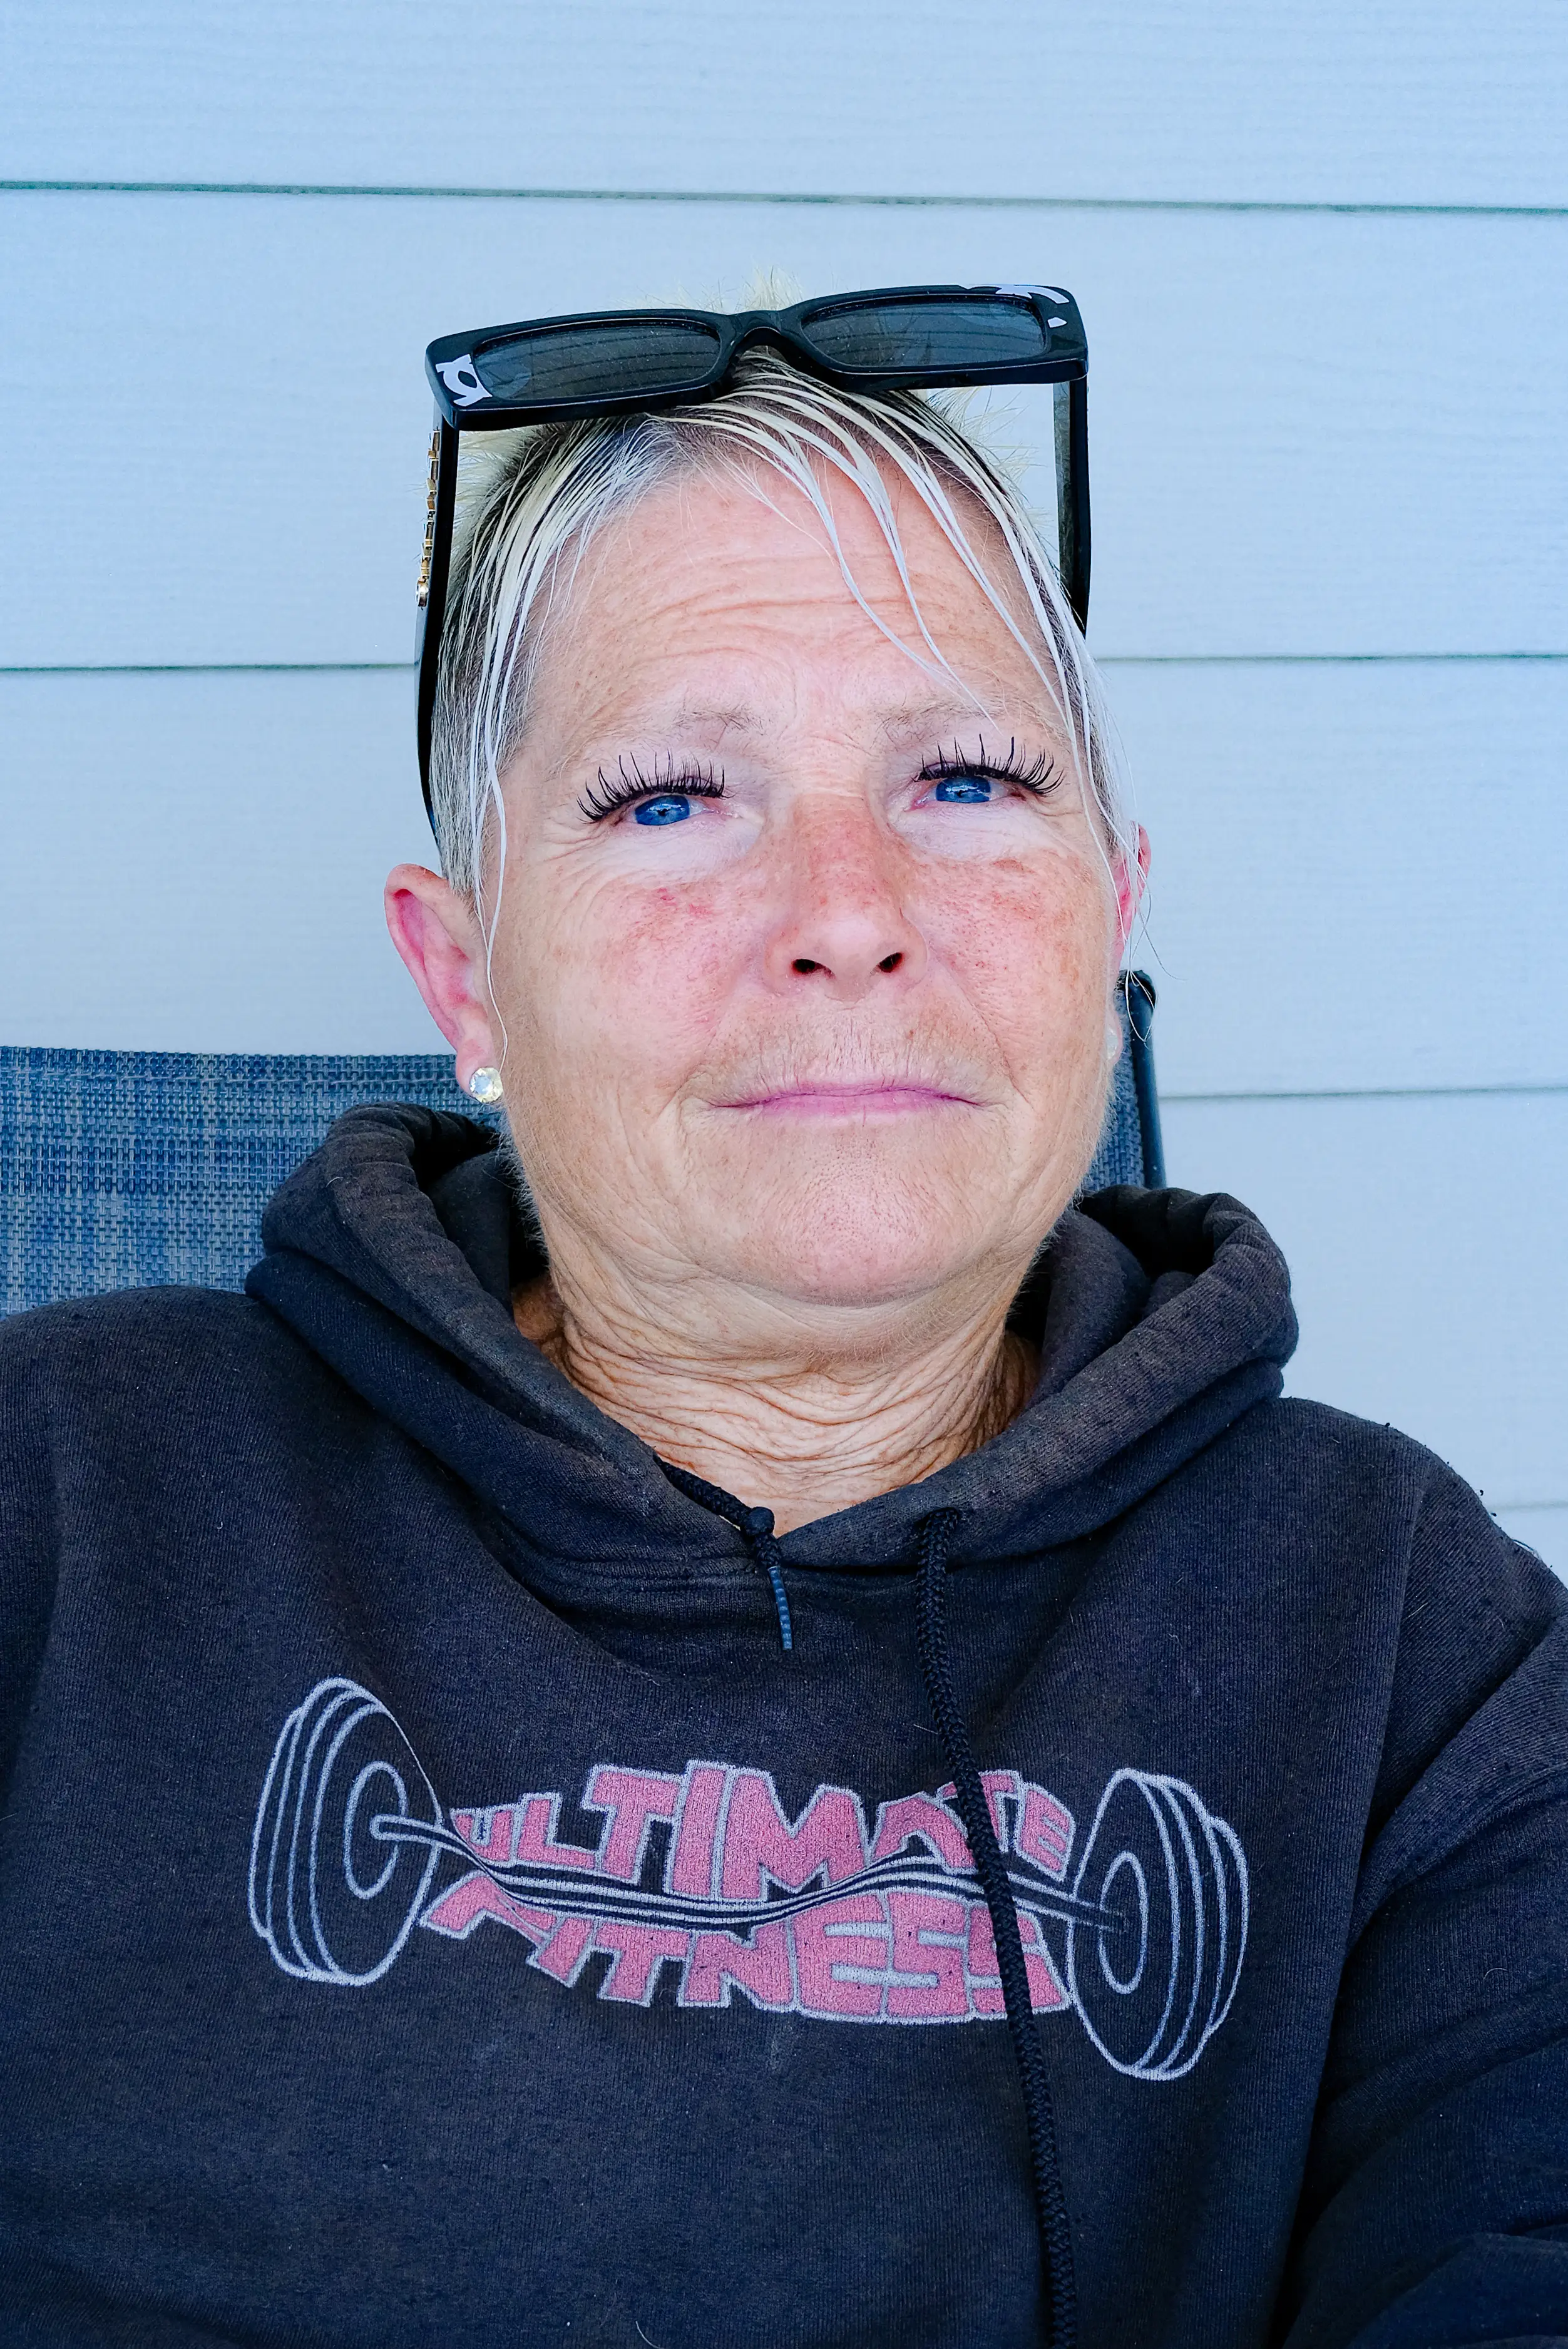
Nansi Lynch never went to college. But she’s approaching retirement with a $156,000 student-loan balance.
“I don’t get rid of it until I turn 75 years old,” Lynch said. “I’ve never heard of something so disastrous in my life.”
The 60-year-old took out federal parent PLUS loans, which carry the highest federal interest rate of 9.07%, for both of her children. Previously, parents could borrow the full cost of attendance. In July, the Trump administration imposed a lifetime borrowing cap of $65,000 per dependent for new parent PLUS loans, in an attempt to address spiraling debt.
Under her pre-existing income-driven repayment plan, Lynch’s monthly student-loan payments were $238. Lynch worries her payments will increase when her forbearance ends early next year. Business Insider has heard from many borrowers who saw their payments jump over the past year, pushing them to take on extra work, postpone retirement, or face the consequences of defaulting.
Lynch doesn’t regret taking out the loans, but she wishes she had considered the consequences of being six figures in debt.
“We thought it was a good idea to take out the parent PLUS because we wanted our kids to get a better education and a better job,” Lynch said — her son is a personal trainer at the gym they own together, and her daughter works full time in security operations for a federal contractor. “But in the long run, I’m stuck with all of the student-loan debt.”
Managing student loans and delaying retirement
Lynch is a high school graduate who has worked as a school bus driver for nearly 30 years. Between the morning and evening bus shifts, she also runs classes at her gym.
When Lynch’s daughter took out loans to attend Salve Regina University, a private Rhode Island college, Lynch helped to cover the cost by taking out parent PLUS loans herself. Her balance grew a year later, in 2012, when she borrowed more for her son’s education at Rhode Island College and a local community college a year later.
Repayment hasn’t been easy. Since Lynch works only her primary job during the school year, she has put her student loans on deferment during periods when she wasn’t working. During that time, interest was still accumulating on her balance.
Lynch wants to retire in the next five years, but she said that doing so isn’t possible while managing her student-loan payments. Trump’s repayment overhaul risks pushing her retirement goals further out of reach.
“I’m still going to have to stay working because how am I going to afford to pay $238 a month if I don’t have any steady stream of income coming in?” Lynch said.
The consequences of debt
Outstanding debt from parent PLUS loans increased from $62 billion in 2014 to nearly $110 billion in 2024, according to the Institute of Education Sciences. Parents have previously told Business Insider that the high interest rate is a key reason they have struggled to pay off their loans, as accumulating interest can leave them with balances far larger than the amount they originally borrowed.
Lynch said that the uncapped borrowing was “problematic” for her, enabling her to take on debt she couldn’t afford while bringing in around $45,000 annually from bus driving.
“You can just keep on applying for more student loan money,” Lynch said. “What happens with that kid after four years? What happens if they can’t get a job and the degree in their field of study?”
Still, the new borrowing caps might not benefit lower-income borrowers, according to a Brookings Institution analysis. It said that “while lower-income families borrow smaller absolute amounts, they face significantly higher debt-to-income ratios.” Thus, borrowing limits might not prevent lower-income families from taking on more debt than they can manage.
Lynch said she sought a loan from the Small Business Administration to move her gym to a better location. The SBA denied her application because she has too much debt in her own name, including both her student loans and a mortgage.
Her kids are concerned about her debt, Lynch said, but she doesn’t want them to help with her payments because they can’t afford it on top of their own bills. She’d rather push off her retirement than have her kids take on the burden.
She wishes that young Americans had better guidance on worthwhile alternatives to a college education.
“I heard from the college kids at the gym all summer long that they couldn’t find a job,” Lynch said. “So you’ve got all these kids that have all this student-loan debt, and they can’t get jobs to pay the bills. The whole thing is broken.”
Read the original article on Business Insider
The post A 60-year-old took out student loans to help her kids succeed. She’s facing retirement with a $156,000 balance. appeared first on Business Insider.