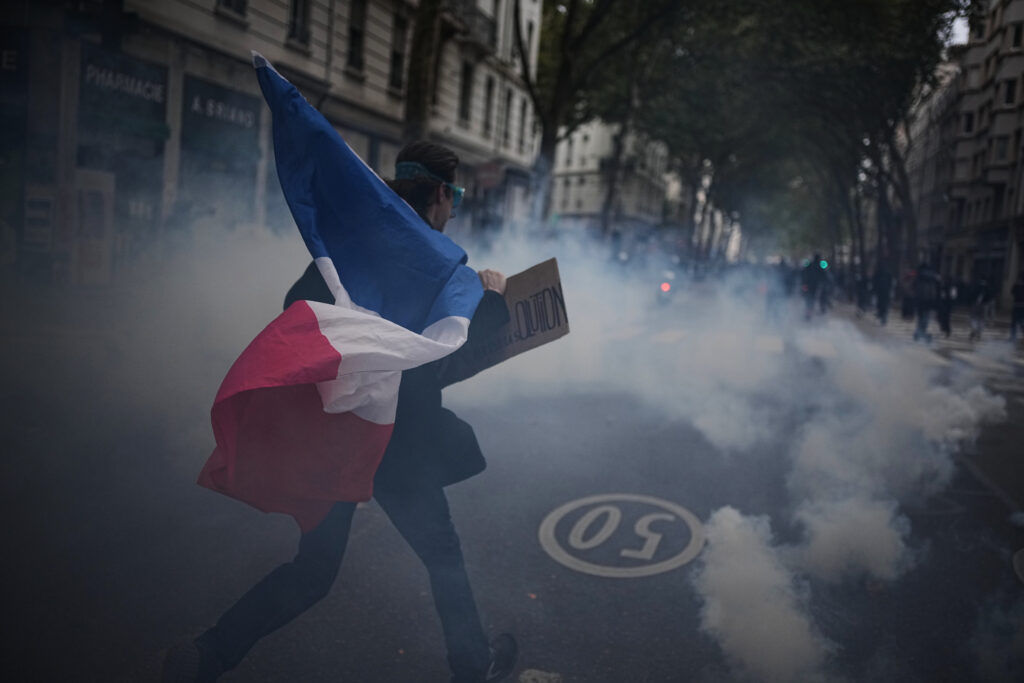
France’s political crisis is colliding with a mathematical one. The government has made expensive commitments that its economy isn’t growing fast enough to keep. Hundreds of thousands of people took to the streets again this weekend to fight for larger slices of a pie that is not getting bigger.
The grievances differ from country to country, but the protests unfolding across Italy, Portugal, Spain and Belgium share an economic backdrop: weak growth, rising living costs and governments struggling to satisfy public demands.
In France, unions are asking for fatter government pensions and paychecks, along with increases in housing assistance, family allowances and a minimum-income benefit. Young people have their own 10-point wish list, which student organizations estimate would cost 10 billion euros ($11.2 billion). It includes 250,000 additional places in public higher education and an extra 2,400 euros ($2,688) a year for students receiving government grants.
Before politicians can redistribute wealth, somebody has to create it. France has neglected the second half of that equation. Its stagnant economy cannot generate enough tax revenue to finance its existing commitments without enormous deficits, let alone cover the protesters’ wish lists. The government is running a budget deficit of more than 5 percent of gross domestic product. Public debt is approaching 120 percent. The International Monetary Fund expects the economy to grow just 0.4 percent this year and 0.7 percent next year.
Government spending amounts to 57 percent of GDP. Nearly a quarter of public spending goes toward retirement pensions. French President Emmanuel Macron pushed through a bitterly contested 2023 reform to gradually raise the retirement age from 62 to 64. But his government partially retreated this year, pausing further increases.
France’s unrest is scrambling politics ahead of next spring’s presidential election. Rioting, looting and chaos provide Marine Le Pen and her National Rally party with issues ripe for a campaign focused on immigration and public disorder. Yet the far-right candidate rejects austerity and supports allowing some workers to retire at 60.
Jean-Luc Mélenchon, the far-left candidate polling in second place, goes further. He proposes essentially wiping away the portion of France’s government debt held through its central bank — about 18 percent of the total — to free up more cash for public spending.
French politicians are not in the habit of looking beyond France’s borders for solutions, but they would do well to consider how Denmark has managed its expansive welfare state. To start, Danish leaders have been more willing to acknowledge that someone has to pay for it. When policymakers realized that an aging population threatened the sustainability of its pension system, they voted to gradually raise the retirement age from 67 to 70 by 2040.
Denmark’s economy grew 2.9 percent last year. Its public debt is less than 30 percent of GDP, and the government ran a budget surplus. Denmark is no laissez-faire paradise. But it demonstrates that fiscal responsibility, a generous safety net and a thriving market economy can coexist. Indeed, the safety net ultimately depends on the economy that finances it.
Ignoring hard choices is a habit of populist parties across Europe. In Germany, the far-right AfD wants to expand access to early retirement and the far-left Die Linke wants to lower the retirement age.
Governments need to attack the debt-to-GDP ratio from both sides. Raising retirement ages and restraining entitlement growth make the debt more manageable. Lowering taxes on work and investment, making labor markets more flexible, cutting unnecessary regulations and tearing down trade barriers help grow the economy. The formula isn’t complicated: Spend less and make it easier to produce more.
Germany’s center-right Chancellor Friedrich Merz is trying to move in this direction. He backs gradually raising the retirement age to 70 as life expectancy grows. His finance minister said last week that strong tax collections provide no excuse to relax fiscal discipline. Merz is also pushing tax, regulatory and energy policies that would make Germany more attractive for investment.
A continent that fancies itself a regulatory superpower should not be surprised when it impedes wealth creation and winds up with less wealth to redistribute. Politicians can ignore arithmetic for only so long because bond markets will not. As investors become more concerned about the government’s ability to pay debts, they demand higher returns for lending. Rising borrowing costs then consume money that could otherwise cover what the unhappy people in the streets of Paris say they want.
The post Europe is running out of other people’s money appeared first on Washington Post.