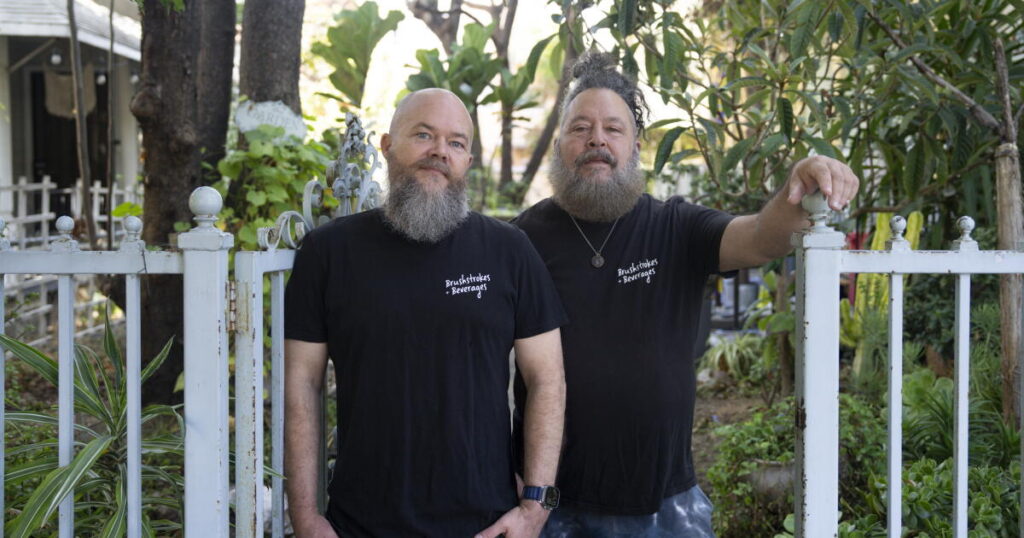
When sales began falling early this year at Brushstrokes + Beverages, a Long Beach “paint and sip” studio, the owners started looking at options to keep their decade-old business afloat.
Michael Mosselli and his co-owner, Marty Meier, had taken out government-backed small business loans in the past. But this time they needed cash faster — and turned to a fix they hoped would carry them through the downturn. Mosselli said it was a decision made “out of desperation.”
Within days last February, the studio owners got $7,200 from a cash advance company based in New York. A couple of weeks later they borrowed more.
The payback agreement required daily withdrawals of a fixed amount of upward of $300 from their business account until the advance and processing fees were paid off, which the company estimated would take almost two months. But they couldn’t keep up with the daily payments, and amassed significant penalties. Eventually, they were forced to shutter their business owing more than $34,000 on the borrowed $11,850.
Mosselli and Meier had agreed to what is called a merchant cash advance, commonly called MCAs, and their circumstances offer a cautionary — and in their case, crushing example of potential pitfalls of this financial tool.
The product is a largely unregulated sector of the financial industry, but one that more small-business owners are turning to as it has become harder to get bank-financed business loans and as tariffs, ICE raids and rising gas prices cut into their revenue. It promises quick cash — but at a high cost.
In 2014, merchant cash advances nationwide totaled about $8.6 billion, according to one federal agency. By 2019, it was estimated the market had more than doubled. Analysts predict the merchant cash advance market could amount to $35 billion by 2030.
Although the money can at times save a struggling business, California lawmakers and bankruptcy lawyers say the terms and costly payback conditions can also thrust mom-and-pop shops into financial turmoil.
Politicians and advocates have spent the last decade pushing for more regulations, including a California bill signed into law last month that requires merchant cash advance companies to be licensed. But this new requirement would not have affected the terms of the advance received by Mosselli and Meier.
“Unfortunately, these MCAs, the way that they’re usually administered, tend to harm small businesses,” said David Chase, a vice president at the advocacy group Small Business Majority. “Maybe the business is already at a disadvantage and then they get into an MCA, which makes things even worse.”
How merchant cash advances work
Increasingly, small businesses like Brushstrokes + Beverages — with little capital to use as collateral against a traditional loan — are turning to nonbank finance companies for merchant cash advances. The financing has become so popular that large retailers, including Amazon and WalMart, partner with third-party companies to offer options.
By operating outside the regulated banking system, MCA issuers are not subject to some of the same state and federal oversight rules that can protect consumers, such as interest rate caps required of government-backed small-business loans.
Mosselli and Meier took out an MCA with a business called Woodmere Capital. Their contract, which the two shared with The Times, made clear that the money they received was not a loan and laid out the repayment terms, including the daily payback amount, interest rates and fees.
The owners agreed to turn over a chunk of their future sales to Woodmere as payback. But when their sales hadn’t picked up weeks later, they decided to take out even more money with the company. They also agreed to have a daily payback amount withdrawn from their business accounts. The finance company estimated they would pay off what they owed in less than two months.
When reached by phone, a man who identified himself as Justin Miller said he was head of Woodmere’s operations and said the cash advance was no different from a mortgage or a credit card. He said that his terms were flexible and that businesses struggling to make the daily payments could request “reconciliation,” where the company evaluates recent sales and recalculates the daily payback amount.
“What these companies say [is], ‘We will give you a lump sum of cash and in exchange you will sell us a certain percentage of your future receipts,’” said Kara Bruce, a law professor at the University of North Carolina, who has written about merchant cash advances. The companies are known for aggressive marketing, often blanketing business owners with dozens of texts, calls and emails a day, she said.
This fast access to cash — sometimes available in one day — can also fill a void. A government small-business loan, for example, can take 30 to 90 days.
MCAs also appeal to business owners without strong credit. According to an annual Federal Reserve survey of small businesses with employees, 4 in 10 business owners who applied for a government-backed loan in 2025 were denied funding, but only 1 in 10 were denied a merchant cash advance.
Among all small-business financing applications submitted in a given year, the percentage of applications for government-backed small-business loans remained steady between 2023 and 2025, but the percentage of applications for MCAs rose from 8% to 12%, according to the federal survey.
Scott Stewart, who leads a trade group that represents online lenders, said MCAs can be useful when a small business needs quick cash to cover an unexpected expense.
“If you have an industrial oven in your business that goes out, you really can’t spend months passing paperwork back and forth,” said Stewart, chief executive of the Innovative Lending Platform Assn.
He acknowledged there can be troubling practices in the industry, but “it’s a useful product for small business,” he said. “Are there bad actors? Absolutely. There are actors loading up companies with debt … [but] I would say that that’s probably a minority of the industry.”
Bruce said it’s often hard to pinpoint who is behind the typical MCA company. Because they don’t have brick-and-mortar operations, like banks, they can crop up with bare-bones business infrastructure.
From quick cash to bankruptcy
Since 2018, California has passed laws to regulate these types of cash advances, including requiring issuers to disclose specific terms, such as the total cost of the financing — which allowed Mosselli and Meier to see the full payback terms of their cash advance.
A law passed in 2023 prohibits small-business lenders from tacking on certain fees, including a fee for processing a payment on the loan or advance.
Because these funds typically have to be paid back over a couple of months, the Brushstrokes + Beverages MCA contract with Woodmere, reviewed by The Times, showed a 32% daily interest rate.
Stella Havkin, a California attorney who represents small businesses filing for bankruptcy, said that over the last decade the number of cases she’s handled for small-business owners with an MCA has “mushroomed.” In 2018, she estimates that 5% of her cases involved owners who had taken out an MCA. Now, at least 70% of cases include at least one cash advance, she said.
The businesses she’s seen rely on MCAs run the gamut of industries from construction to apparel and tend to be very small, with no more than a few employees, she said.
Two other attorneys who specialize in serving small businesses said they’ve seen a significant uptick in bankruptcy cases that include MCAs. Often, the businesses taking out this fast cash were already struggling, attorneys said.
“It’s accelerating something that was already on the way of happening and then it makes the situation worse,” said John-Patrick M. Fritz, a partner at an L.A.-based law firm that handles small-business bankruptcy cases.
That’s what happened with Mosselli and Meier. When grocery and gas prices began to rise, customers stayed away from the “paint and sip” shop. Their income dropped by more than half, they said.
At first, the money they borrowed would be paid back in daily debits of $300, and then $405 over a span of about two months, until Mosselli and Meier repaid the debt — a total of more than $20,000 on the $11,850 advance.
But by the end of March and a month after getting their initial cash infusion, they were struggling to keep up with the daily payments. They put a stop on withdrawals and emailed Woodmere saying they were no longer authorizing automatic payments.
According to copies of messages shared with The Times, they received a text back two days after they stopped payments stating the company was “Aggressive on collecting,” and would be taking a series of actions, including freezing and garnishing all their assets and using a private investigator to go after “[f]inancial wrongdoings.”
Meier responded to the text saying that sales had significantly declined, that the current repayment structure didn’t reflect actual business and they couldn’t afford the daily withdrawals.
In response, they received a message asking: “What can you pay daily instead.”
Meier and Mosselli said they did not ask about the reconciliation Miller mentioned and they did not text back, saying they were “shocked” by the text exchange laying out the aggressive collections strategy. Unable to continue paying rent, they decided to close their shop in July.
They estimate they’ve paid back roughly $6,400 of the nearly $12,000 in cash they received, but still owe about three times that. Since stopping payment, they’ve had liens placed on several accounts, including a PayPal and Groupon account, which cut them off from additional revenue.
They acknowledged that they may not have fully understood the MCA agreement when they signed it, but said they felt they had no other option to keep their business going.
State records show that Woodmere Capital, the finance company, first registered as a business in New York in 2024. According to Nassau County property records, the company’s listed address is a single-family home.
Woodmere is registered to a Joseph Wallin, according to New York business registration records. When a Times reporter emailed the company, Miller called back and defended the business.
“It’s not predatory just because we’re purchasing receivables on it,” he said. “It’s the same way how you go to American Express and you pay a credit card and you pay a percentage of your daily receivables.”
A collection agency last month told Mosselli and Meier they have an outstanding balance of $34,800. The owners couldn’t say with certainty what caused their balance to balloon. But the contract lays out various fees that could have inflated the amount owed, including $5,000 for defaulting and another $5,000 for blocking access to a bank account.
Attempts to regulate
Last month, Gov. Gavin Newsom signed Assembly Bill 2116, authored by Assemblywoman Pilar Schiavo (D-Chatsworth), which requires companies issuing merchant cash advances to be licensed as commercial financing providers with the state’s Department of Financial Protection and Innovation. It also broadly forbids these companies from misleading or deceiving customers and prohibits confidentiality agreements.
Supporters say licensing will give California the authority to act on any complaints, and to investigate and penalize companies for unfair or deceptive practices.
Industry representatives who opposed the bill said that regulations like these could make it harder for them to extend a necessary lifeline.
Today, Mosselli and Meier are operating their business as a mobile studio, pulling in minimal revenue. Several of their liens have been lifted, but their debts have been sent to collection agencies that specialize in recovering MCA debt.
The other night while working an event, Meier noticed a man trying to tow their truck. It turns out, he was trying to repossess it because they hadn’t been able to make the lease payments. Meier was able to talk him out of it, he said, and he left the truck. But, given the hefty amount they still owe on the MCA, the partners are now considering filing for bankruptcy.
“I’m 60 years old,” Mosselli said. “I wasn’t expecting to do this at this point in my life.”
This article is part of The Times’ equity reporting initiative, funded by the James Irvine Foundation, exploring the challenges facing low-income workers and the efforts being made to address California’s economic divide.
The post Desperate mom-and-pops turn to risky cash advances in tough economy — and can get burned appeared first on Los Angeles Times.