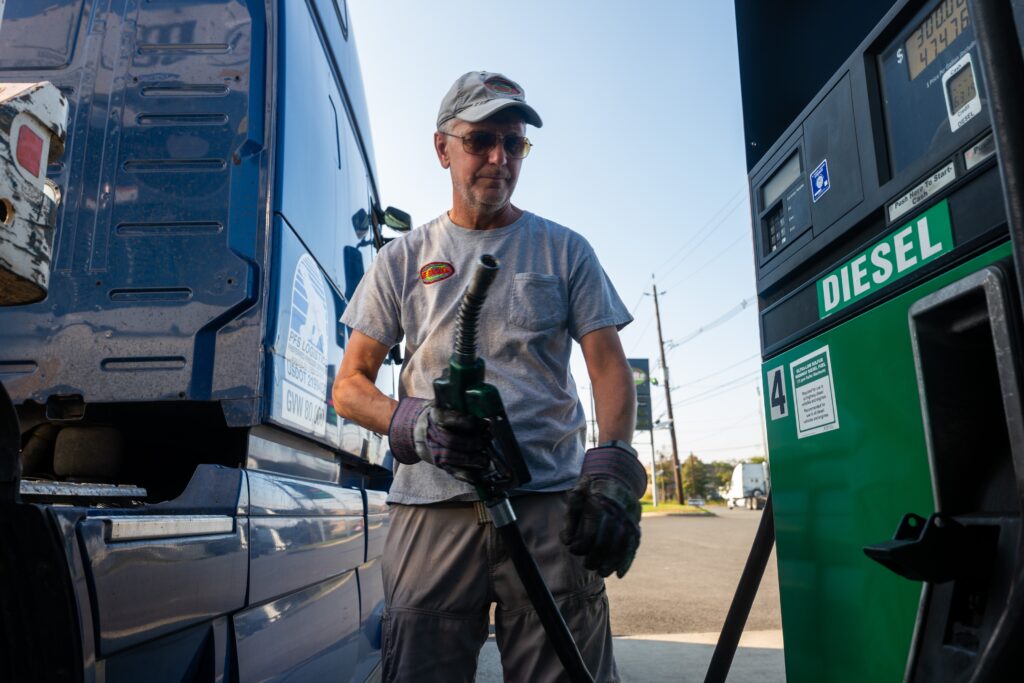
Since President Donald Trump returned to the White House 21 months ago, gas is up about $1.20 per gallon and mortgage rates have soared past 7 percent, hitting a three-year high.
On the other hand, the unemployment rate is still low and eggs no longer cost more than $6 a dozen.
With midterm elections just a week away, Trump’s approval rating for handling the economy has plummeted. For the first time in more than a decade, polls show that voters trust Democrats more on the economy — the issue they say they care about most.
But how has the economy really changed under Trump? We take a look in these 13 charts.
Economic growth is steady
Buoyed by strong consumer spending and business investment, the economy has proven resilient this year, despite energy shocks and persistent inflation.
Though overall economic growth slowed slightly in the second quarter, the U.S. economy is growing at a stable 2.2 percent rate. This is not much different than under President Joe Biden, since the rockier measurements during the pandemic have evened out.
Business investment made up a significant portion of gross domestic product growth, bolstered by the artificial intelligence boom and data center build-out. Figures for the third quarter — which should reflect continued effects of the Iran war — are expected to be released before the Nov. 3 election.
The stock market is strong
The market has been a bright spot in the economy this year, especially for Americans who own stocks. The S&P 500 index hit a new high earlier this month, propelled in part by bets that massive corporate spending on AI will pay off.
But economists note that many Americans do not directly benefit from these gains, which may explain why the strong market has not done more to bolster Trump’s approval rating.
“If you’re in the top 20 percent and you own AI stocks, you’re doing well — the economy feels great to you,” said Mark Zandi, chief economist at Moody’s Analytics. “If you’re in the bottom 80 percent of income distribution, you don’t own much stock, you may or may not own a home and you are focused on declining after-inflation wages, then it’s a tough economy.”
The federal debt is growing fast
The federal debt also hit a new high in August, reaching $40 trillion months earlier than expected in part because of lost revenue from Trump’s invalidated tariffs. Trump also signed a big tax cut law last year and has sought billions in new spending for immigration enforcement and the war in Iran, among other priorities.
About 20 percent of the debt is money the government owes itself. The other 80 percent, mostly sold as bonds to investors, is known as debt held by the public. As of the first quarter of this year, federal debt held by the public stood at 98.7 percent of the overall economy, according to the Office of Management and Budget, and was rapidly approaching the previous peak at the end of World War II.
The faster accumulation of debt comes as an array of concerns — inflation, the war in Iran, rising government debt levels around the world — are causing government bonds to look less appealing. As a result, investors are demanding higher rates of return, or yields.
Last month, the 10-year Treasury yield, a benchmark that influences mortgage rates and other borrowing costs, rose above 5 percent and has remained elevated ever since. In the fiscal year that ended in September, the government paid more than $1 trillion in interest on the debt, according to the U.S. Treasury— 14 percent of total federal spending.
Inflation is still elevated
Perhaps the biggest economic issue plaguing Americans is the rate of inflation, which has remained stubbornly above the Federal Reserve’s target rate of 2 percent for more than five years.
Driven skyward during the pandemic, inflation was finally beginning to settle down when Trump took office last year. But then in February, the U.S. and Israel invaded Iran and inflation rebounded. In September, it reached an annual pace of 3.7 percent — due largely to spikes in energy costs.
Relentlessly rising prices have soured Americans on the economy and made affordability a central issue in the midterms. Trump won the 2024 presidential race on a pledge to bring down everyday prices, and while some categories have seen price drops, many others are still climbing.
Trump has frequently touted two categories where prices have fallen: eggs and prescription drugs. Egg prices have dropped fast as flocks have recovered from an avian flu outbreak. Prescription drug prices are also down, due in part to reforms adopted under Biden.
Gas prices are surging
Prices at the pump have spiked about 37 percent since Trump took office last year, in one of the most visible effects of the Iran war. Rising energy prices have eaten into Americans’ budgets, raising the cost of getting to work or the store and contributing to rising prices for goods and groceries.
Diesel prices hit a record in September, at more than $6.50 per gallon. The fuel is used to power agricultural machines, trucking and plastics production, bleeding into the price of many household goods.
Trump has considered multiple options for lowering energy prices, including a ban on diesel exports and a suspension of the federal gas tax, neither of which has been implemented. Earlier this month, he said he struck a deal to obtain diesel from Russia, a stunning reversal of years of U.S. pressure on Moscow over its war with Ukraine.
“The President has always been clear about temporary disruptions as a result of the Iran conflict, but this administration will continue to deliver economic wins for the American people over the next two years,” White House spokesman Matthew Middleton said in a statement.
Mortgage rates are up
Mortgage rates hit 7.4 percent this month for a 30-year home loan, the highest level in three years. Rates had dipped below 7 percent when Trump took office, and fell throughout the first year of his second term.
Many housing economists had expected rates to be around 6 percent by the end of this year, but surging Treasury yields and rising inflation reversed that trend. In an effort to tame inflation, the Federal Reserve last month raised interest rates for the first time in more than three years — a move that also has an indirect effect on mortgage rates.
The rising mortgage rates have made it even harder for many Americans to break into the housing market, where prices nationally also are still rising, though at a slower rate than in recent years.
Hiring is flat
If you have a job, you’re in a good spot. If not, it can be hard to find one, especially for new college graduates.
Economists describe the current labor market as a “low-hire, low-fire” environment. Hiring has largely stagnated, with many of the gains coming in the health care industry. But layoffs also are at low levels: New filings for unemployment benefits have been at or below 200,000 for six weeks, the longest such stretch since the late 1960s.
“While workers searching for their first job or looking for a better one are having a hard time, those already in work have remarkably good job security,” Bill Adams, chief U.S. economist at Fifth Third Commercial Bank, wrote in an analyst note this month.
Unemployment remains low
Though hiring has cooled this year, the unemployment rate has held steady since Trump took office.
Apart from a huge covid-fueled spike during 2020 and 2021, the unemployment rate has stayed relatively low through both Trump’s and Biden’s presidencies. Two factors supporting that trend: baby boomers retiring and immigrants facing new work restrictions.
The low unemployment rate has helped keep the economy stable, economists say, as people who have jobs feel comfortable spending money, even as prices rise.
Wages have fallen behind inflation
Americans have seen no real wage growth on average since the start of Trump’s second term, according to data from the Bureau of Labor Statistics. Between January 2025 and September 2026, both prices and average hourly pay have risen by about 5.4 percent.
And average hourly earnings fell 0.5 percent from August to September as energy price spikes fed into inflation.
That means people’s purchasing power is eroding, leaving many feeling they are falling behind financially. “Around the kitchen table, the resilience of the U.S. economy is not resonating,” said Diane Swonk, chief economist at KPMG.
Consumers are still spending
Though Americans are feeling increasingly dreary about the economy, they are still opening their wallets. Consumer spending has remained strong since Trump returned to office, ticking up 0.9 percent in August.
The stable labor market plays heavily into spending trends: If people are employed and feel their jobs are secure, they are more comfortable spending even as prices rise. Wealthier Americans also are buoyed by a strong stock market. And many households received higher-than-usual tax refunds this spring as a result of tax cuts in Trump’s One Big Beautiful Bill Act.
But there’s evidence that people are dipping into their savings to keep up. In August, the personal savings rate fell to its lowest level in nearly four years.
The post Trump’s economy, in 13 charts appeared first on Washington Post.