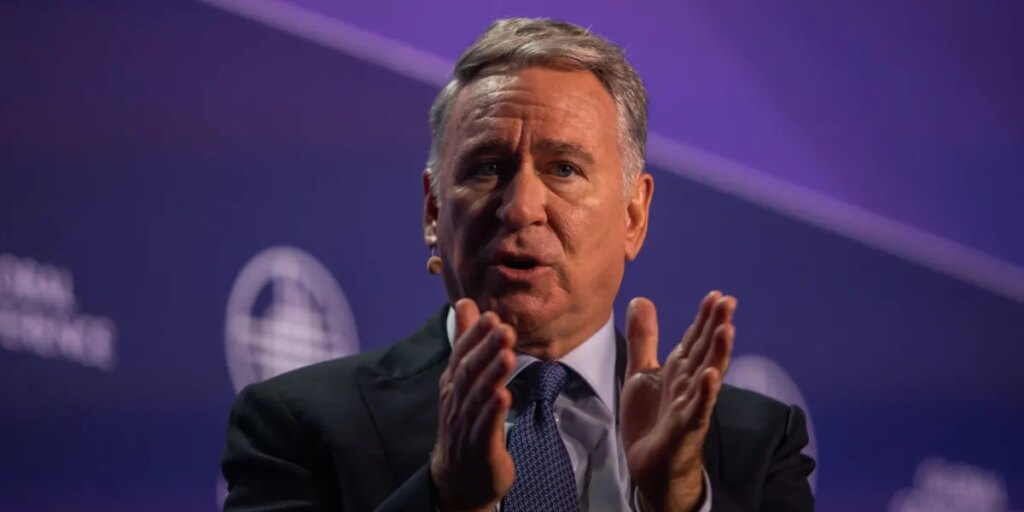
Ken Griffin has spent millions helping Republicans win elections. But the Citadel founder says President Donald Trump and his party made a mistake by renewing tax cuts without room in the budget to pay for them.
“We didn’t have the fiscal space to renew the tax cuts,” Griffin said Tuesday at the Future of Global Markets Conference in New York, pointing to the government’s heavy pandemic spending and a national debt that has surpassed $40 trillion.
His criticism centers on Trump’s One Big Beautiful Bill Act, which kept the lower individual income tax rates from the president’s 2017 overhaul permanent, instead of letting them expire at the end of 2025. Along with preventing that tax increase, the law added deductions for qualifying tips and overtime pay, as well as certain auto loan interest.
However, preserving those savings for taxpayers also means Washington collects less revenue than it would have if the cuts had expired. With the government already spending more than it brings in, Griffin’s concern is that Republicans extended the relief without enough room in the budget to absorb the cost.
His criticism hasn’t stopped him from putting millions behind the party, including $10 million to the Senate Leadership Fund and $5 million to the Congressional Leadership Fund this election cycle to help Republicans secure seats in both chambers of Congress. He also gave $10 million in support of Florida’s gubernatorial nominee, Byron Donalds.
The cost of keeping taxes lower
The cost of the legislation extends beyond the revenue Washington gives up, and borrowing to cover the gap also means paying interest.
The Congressional Budget Office estimated that the law’s tax and spending changes would add $4.1 trillion to federal deficits over 2025–2034, including interest on the additional borrowing. That estimate does not account for how the law’s effects on the economy could change federal revenue and spending.
Those projected costs add to a debt burden accumulated under both Republican and Democratic administrations, now totaling approximately $40.4 trillion. That includes debt held by investors and obligations to government accounts.
And the interest bill is growing, too. As Fortune reported last week, annual net interest payments reached $1.05 trillion in fiscal 2026, up 8% from the previous year. Unless Washington brings in more revenue or cuts spending elsewhere, covering those payments adds to its borrowing needs.
Griffin’s warnings go beyond tax cuts
Griffin has been questioning Washington’s economic choices for some time. In October 2025, he described the economy as being on a “sugar high,” saying government policies were providing a boost more suited to a recession. By January 2026, he was warning that bond investors could punish governments that failed to get their finances in order.
If investors demand higher interest rates to keep lending to Washington, the government would have to pay more when it takes out new debt or replaces debt coming due, adding to its already growing interest bill.
When asked how to put the country’s finances in order given politicians’ reluctance to cut spending or raise taxes, Griffin turned to productivity. “We really need to play the productivity card as hard as we can,” he said.
For Griffin, that means supporting AI and building data centers in America, while also pursuing advances in nuclear energy, batteries, and robotics. He called for more attention to technologies that could improve productivity over the next 20 years, saying that should be the administration’s central economic focus.
He wants America’s allies to pursue growth, too, arguing that Washington should push Europe toward economic reforms rather than fight a tariff war he called “a fiasco.”
“The entire Western world is in the same boat together,” he said.
For the U.S., he put the priority bluntly: “grow the damn economy.”
The post ‘Grow the damn economy’: Billionaire Ken Griffin warns Trump made a mistake cutting taxes as the national debt tops past $40 trillion appeared first on Fortune.