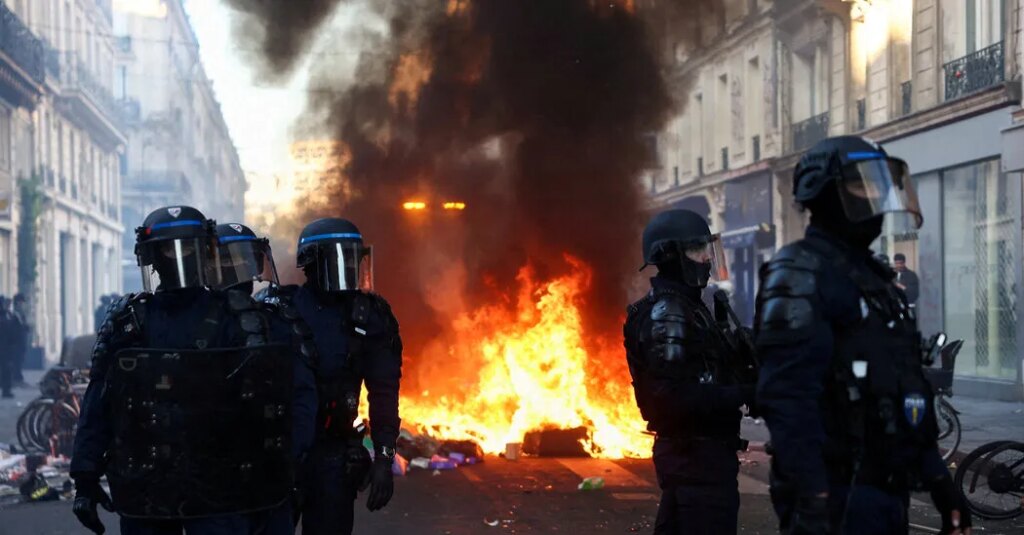
When protests over high gas prices ripped through France in 2018, President Emmanuel Macron offered to enact about $11 billion in tax cuts and wage increases to try to quell the unrest.
Today, after protests over education turned violent, Mr. Macron is in no position to use money to bring calm to the streets.
That’s because the French government is also fighting the prospect of a crisis in its bond market. Investors have been dumping French debt, unsure of the government’s ability to manage its budget amid high interest rates and political uncertainty.
Announcing a big financial commitment to mollify protesters would likely rattle investors further and lead to another jump in the government’s borrowing costs. Mr. Macron, approaching the end of his time in office, is leading a centrist government without a governing majority. He is left in a tight spot: Both inaction and more spending could exacerbate France’s troubles and give populist politicians running for his seat next year a bigger opening to attract aggravated voters.
France is not the only country facing a debt trap. As borrowing grows in many wealthy nations, populist political parties are surging. Experts warn the mix could combust into an economic crisis.
Governments face a “doom loop,” in which market turmoil and political tumult feed off each other, according to Michal Brzozowski and Joanna Siwinska-Gorzelak, researchers at Poland’s University of Warsaw, who published a research paper on the relationship between populism and fiscal policy.
“The risk is less about a sudden debt default and more about a slow-motion economic drag,” they wrote in an email.
At the root of the problem is a considerable tension: Amid deep political and fiscal uncertainty, voters and investors appear to want different things.
Buyers of debt want to be adequately compensated for the risk of lending to governments. In turn they are shunning lawmakers who seem unable to make difficult choices, such as spending cuts or tax increases, to reduce yawning budget deficits. They are demanding higher interest payments, amid expectations that governments will keep borrowing a lot. This dynamic is unfolding most forcefully in France, but Germany, Japan and the United States are also contending with higher borrowing costs.
Voters, though, are increasingly turning to populist parties that largely reject the idea that budgets require painful trade-offs. Instead, they promise to protect generous retirement programs and other spending, while often proposing to cut taxes.
The resulting tension could spiral like this: Economically anxious voters turn to extreme populists, who promise a pain-free return to better days, and buyers of government debt recoil.
In France, the government bond yields, a measure of borrowing costs, have climbed to the highest since 2002. And in another worrisome sign, the gap between yields on French and German 10-year government debt has jumped to its widest since 2011. German yields are typically lower than French ones, but the growing difference shows that investors are demanding an ever higher premium to hold French debt.
Not all of the turmoil in bond markets comes from government policies. One of the largest triggers for rising bond yields worldwide has been the U.S.-Israeli war with Iran. Higher energy prices have revived inflation and forced several central banks to raise interest rates.
No matter the cause, higher yields aggravate the already difficult situation facing some governments, which must spend more on debt interest payments at the expense of other priorities like education.
In Europe, where economic growth is lackluster, fiscal policy must do much of the hard work of reducing debt burdens. But raising taxes or cutting spending has been frequently met with strong public resistance because people already feel overtaxed and demand more in public services and welfare benefits.
Eventually these problems will come to a head, said Simon Radford, the director for policy and programming for the Milken Institute in Europe.
“If you’re not going to solve it with new growth, and if interest payments are outrunning growth, then eventually what can’t go on forever, won’t go on forever,” he said.
The turmoil in France began as demonstrations by high school students who wanted better classrooms and more teachers. Protests over the cost of living and funding for education and other services have spread through Europe, including in Belgium and Italy.
These financial troubles are particularly a problem for centrist political parties, said Ludovic Subran, the chief investment officer and chief economist at Allianz, the German insurance company. In many cases, these politicians want to use pledges of fiscal discipline to attract voters. But it often doesn’t work and instead and can leave the public with the impression that those politicians are largely powerless to improve conditions, he added.
“That’s really the Catch-22 of politics today,” Mr. Subran said. The politicians who have felt the disciplinary hand of the market are punished politically. “Then it gives extreme parties a boulevard to say whatever they want to say,” he added.
In Germany, the far-right Alternative for Germany party, or AfD, won a pair of state elections last month and now leads national polls. Its leaders have criticized the incumbent government, led by the center-right Chancellor Friedrich Merz, for proposals meant to shore up future budgets — including changes in some pension plans and a gradual raising of the retirement age.
In Britain, the center-left Labour government has been trying to fend off the rise of Reform U.K., a far-right party led by Nigel Farage. Earlier this year, as Reform led in the polls, the Labour Party ousted Keir Starmer as prime minister, who prioritized keeping bond markets calm, in favor of Andy Burnham, a mayor from a city in Northern England who promised sweeping changes to how the country was run.
France is at the sharp end of this predicament in Europe.
Even in 2018, Mr. Macron’s plan to stop the protests caused tremors in the bond market. The government promised its extra spending would be paid for by budget cuts and the deficit would stay in line with European limits. Today, the fiscal situation is much tougher. The annual budget deficit and the public debt, which is nearly 120 percent of the size of the French economy, are much larger than they were in 2018.
While holding emergency meetings about the protests, France’s prime minister, Sébastien Lecornu, is trying to pass a budget for next year to narrow the deficit. But his minority government is facing stiff opposition as parties prepare for a presidential election in about six months. The far-right leader Marine Le Pen is the current front-runner, and polls suggest that she would face off against a far-left candidate.
Though Ms. Le Pen has proposed a vow to reduce the deficit, economists question the credibility of her financial plan, which would lower the retirement age while slashing spending on state bodies and cutting the country’s contribution to the European Union. All those measures would be difficult to enact. Jean-Luc Mélenchon, the far-left candidate, has alarmed investors by proposing to effectively cancel some of the country’s debt instead of repaying it.
France faces “triple uncertainty” because of budget negotiations, the presidential election and legislative elections that are likely to follow soon after, said Mr. Subran, the Allianz economist. Therefore, France’s bond yields might not come down soon.
“A lot of people are holding their breath,” he said.
The cost of high yields will be felt quickly. The French government expects to spend more than 90 billion euros ($100 billion) on debt interest payments next year, which is more than planned spending on defense and education, according to the French finance ministry, another political headache.
The post A ‘Doom Loop’ Threatens France as Populism Confronts Markets appeared first on New York Times.