Ahead of the midterm elections, The Washington Post is offering snapshots of voters across the country who cite affordability as a top concern. Here is the second in the series.
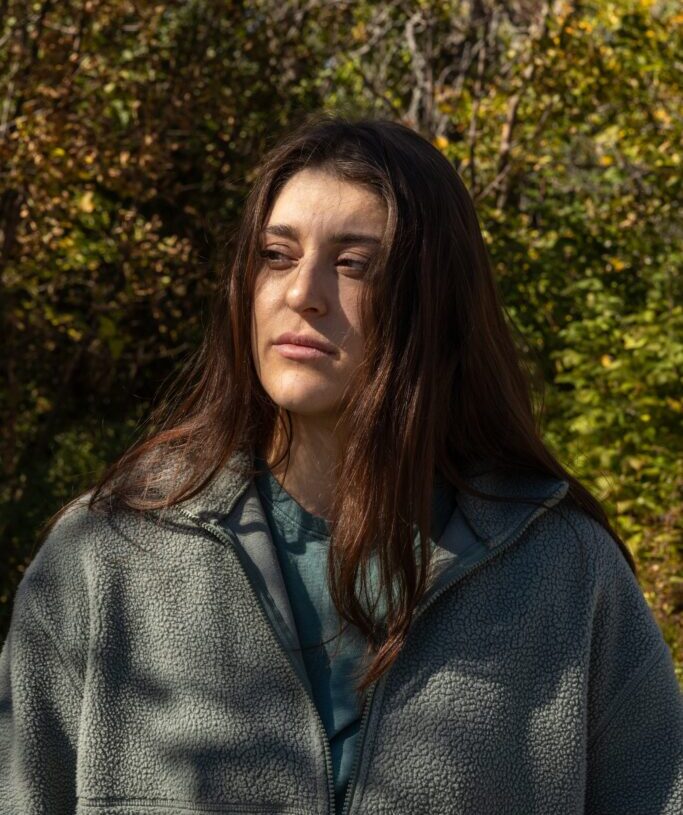
Ellie Pierotti considers herself fortunate: At 30, she’s earning more money than she has at any point in her life. She can afford her own apartment and recently took out a loan on a new car. She lives in a state she loves, the place where she was born.
Yet she can’t quite get ahead.
The price of everything — housing, groceries, gas — keeps rising. Recent health challenges left her struggling with unpaid medical bills. She has more than $60,000 in student loans.
“It’s never felt like I’ve not had the money stuff weighing on me,” Pierotti said. “Even working in a good job where you’re making money.”
For the past year, Pierotti has earned $75,000 as a full-time nanny to two toddlers. She has worked in child care since she left home at 18. At the time, she said, college wasn’t for her. She has dreams and aspirations: finishing her bachelor’s degree, maybe saving enough to buy a house.
But the latter feels far out of reach. “I’m trying to pay my bills, my groceries, my gas, my car note,” Pierotti said. “Where can we save money?”
Financial snapshot
Annual income: $75,000
Age: 30
Profession: Nanny
Monthly rent: $2,000
Biggest financial worry: Debt
When Pierotti, a consistent Democratic voter, goes to the polls in November, she’ll be thinking about the cost of living, but even more about the direction of the country and the state. In Maine’s crucial Senate race, she plans to vote for Troy Jackson, the Democratic challenger to Sen. Susan Collins, the Republican incumbent who is seeking her sixth term.
“I don’t think Senator Collins is good for us anymore at all,” she said. “It’s been too long.”
A recent Washington Post-Schar School poll found that Maine voters believe Jackson would do a better job than Collins in addressing the rising cost of living. Voters in the state ranked the issue as their top concern in the midterms, listing utility bills, gasoline prices, health care and grocery costs as unaffordable.
Pierotti was first eligible to vote in a presidential election in 2016, when Donald Trump won. She didn’t cast a ballot that year and hasn’t forgiven herself. She has voted assiduously since. She’s been on plenty of dates, she said, and is frustrated when men tell her they didn’t vote or aren’t political.
“If you care about this country, then you’re political,” Pierotti said.
To save money, Pierotti recently moved from Portland to South Portland, across the Fore River. Portland itself feels increasingly unaffordable, she said. Developers keep building high-rises, and one-bedroom apartments in once-reasonable neighborhoods in the city’s east end are going for $2,500 a month.
Pierotti welcomes those relocating to Maine. But she’s also uneasy, as if the economy is geared toward someone else.
“It hurts my soul that the Mainers who want to live in the city can’t,” Pierotti said.
She has struggled at times. At her previous nannying job, she earned considerably less money and had to rely on help from family members to make her car payments.
When she was between jobs, Pierotti was briefly without health insurance, a lapse she wasn’t aware of until she went to an urgent care center with an asthma flare-up. The receptionist told her she’d be surprised how many people find themselves in the same situation.
Debt, present and future, is Pierotti’s biggest financial worry. One of her medical bills is in collections. She tries to pay off a big chunk of her credit card balances each month, knowing that she sometimes needs to rely on them in emergencies, such as an unexpected car repair or a vet visit for her cat. She still carries a roughly $3,000 balance.
Next year, she is set to graduate from the University of Southern Maine with a degree in communications. She borrowed about $63,000 for tuition. “My brain is really freaking out about student loans,” she said.
For Pierotti, economizing is a daily activity. Maybe it’s not getting takeout for dinner. Maybe it’s cutting back on grocery items, like ice cream, that could be considered an indulgence.
She’s shocked that trips to the supermarket can cost $50, even when buying for one. She constantly questions what she puts in her cart.
“Wow, that’s $9, do I really need that?” Pierotti said. “I don’t feel I should need to ask myself that about granola.”
When she splurges, she tries to make sure it’s on items she really values. A winter coat from L.L. Bean that will last years. A natural skin care product she swears by. A three-day trip with girlfriends. She gives herself leeway for the occasional night out with friends, although that too has become an expensive proposition (up to $200, she estimates, for a nice dinner, drinks and dancing.)
Pierotti has $1,000 socked away in her emergency fund. She has read that it’s not nearly enough — that she needs to save at least three months’ worth of expenses.
Her short-term goals are to save more and pay off her credit cards. She’ll worry about the student loans next year. Meanwhile, she’ll keep trying to get closer to the kind of life that feels out of reach — one that is “comfortable, stable, responsible, prepared,” Pierotti said with a small laugh. “So many adjectives you could put in there.”
Affordability in America
Why a retired teacher has cut back on food, trips and electricity
The post How a nanny with medical debt is struggling to get ahead in Maine appeared first on Washington Post.